Global wind market growth accelerates as Chinese turbine manufacturers expand abroad
The wind turbine manufacturers landscape is undergoing a profound transformation as Chinese OEMs continue their rapid expansion beyond domestic borders. In 2025 alone, Chinese companies tripled their overseas deliveries and installations, reaching a record 8.5 GW across 22 countries.
This expansion is particularly visible in emerging markets across Central Asia, the Middle East, Africa and South America, where demand for cost-effective and rapidly deployable solutions remains high. At the same time, China confirmed its dominance at home, installing 100 GW of new wind capacity in 2025, becoming the first market ever to reach this threshold in a single year.
Cost leadership and scale drive Chinese wind turbine manufacturers
The success of Chinese wind turbine manufacturers is rooted in an aggressive commercial strategy built on scale, competitive pricing and fast implementation timelines. After saturating the domestic market, Chinese OEMs are leveraging these advantages internationally, supported by the rollout of larger and more powerful offshore turbines in the 16–18 MW range.
This approach reflects a broader industrial strategy focused on expanding manufacturing capacity and securing a strong foothold in high-growth regions, where infrastructure development and energy demand are accelerating.
Western OEMs shift strategy to protect margins
Western wind turbine manufacturers have responded by recalibrating their competitive positioning. No longer competing on volume, European and US players are focusing on fewer markets, prioritizing technological quality, proven platforms and advanced solutions such as predictive maintenance to enhance asset performance and reliability.
This strategy allows them to avoid price competition while maintaining higher profit margins. As a result, Western OEMs secured 75% of wind installations across nearly 50 countries outside China, according to Wood Mackenzie’s latest analysis, “Global wind turbine OEMs 2025 historical market share.”
Top wind turbine manufacturers ranking in 2025
The global ranking of wind turbine manufacturers highlights the dominance of Chinese companies, which occupy 9 of the top 15 positions:
- Goldwind – 29 GW (China)
- Envision – 22 GW (China)
- Windey – 19 GW (China)
- Mingyang – 19 GW (China)
- SANY – 15 GW (China)
- CRRC – 11 GW (China)
- Vestas – 11 GW (Denmark)
- DEC – 11 GW (China)
- GE Vernova – 7 GW (United States)
- Nordex – 7 GW (Germany)
- SEWPG – 7 GW (China)
- Siemens Gamesa – 6 GW (Spain/Germany)
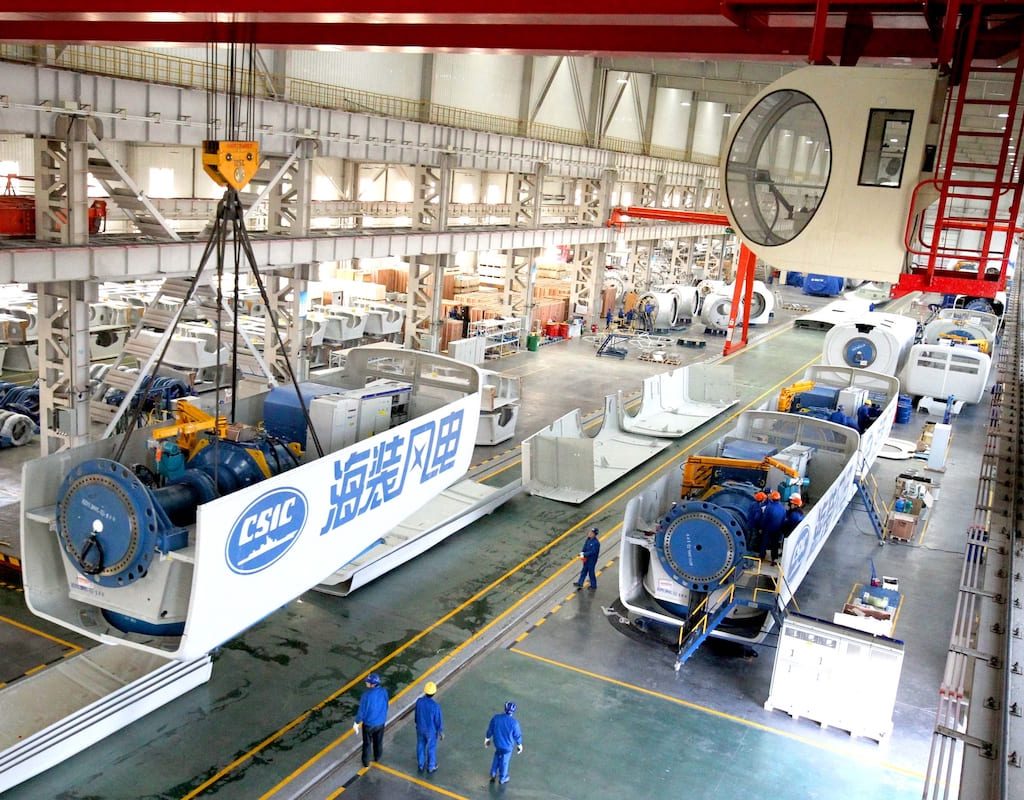
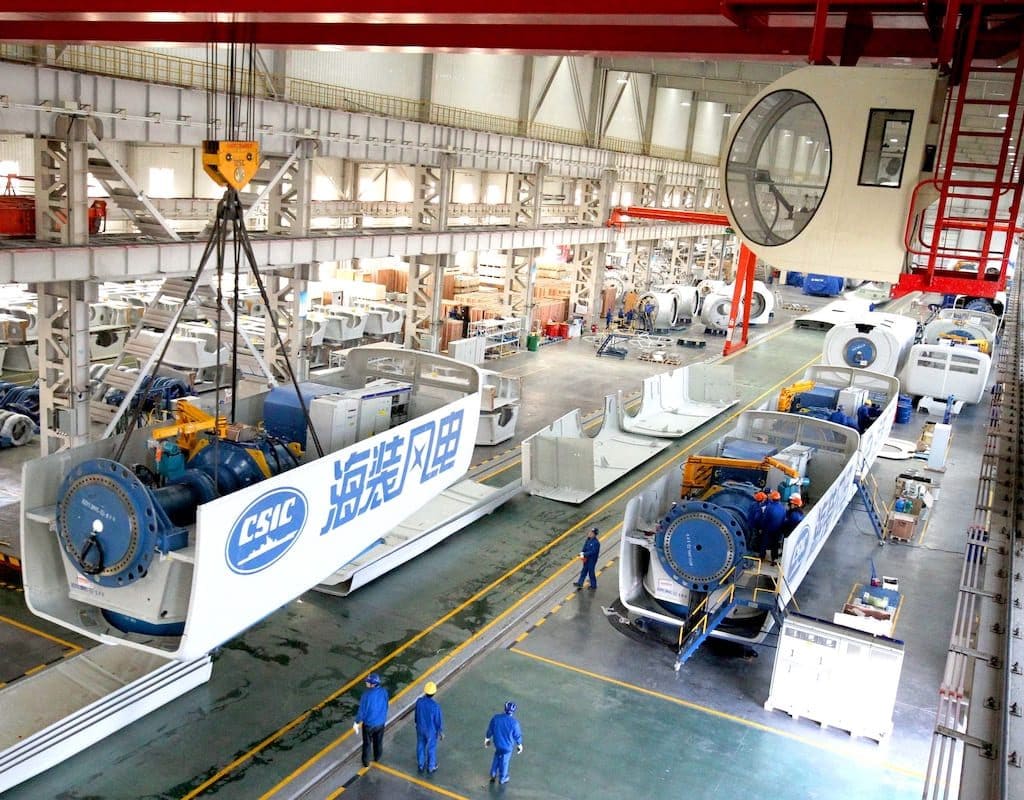
- CSSC Haizhuang – 4 GW (China)
- Enercon – 4 GW (Germany)
- Suzlon – 1 GW (India)
“Goldwind and Envision were the standout performers” Wood Mackenzie notes. “For the first time, two turbine manufacturers exceeded 20 GW of installations. Their momentum reflects a strategy based on economies of scale, competitive pricing and rapid deployment.”
Global wind market balance shifts beyond China
When excluding China, the competitive landscape changes significantly. Denmark’s Vestas remains the most internationally diversified player, delivering turbines across nearly 40 markets in 2025.
At the same time, regional manufacturers are showing renewed strength. India’s Suzlon has re-entered the global top 15, while other Indian OEMs have secured positions among the top suppliers in markets outside China.
This trend underscores the continued relevance of local players, supported by favorable policy frameworks and growing electricity demand. However, Chinese wind turbine manufacturers are expected to intensify competition globally, challenging both regional and established Western leaders.