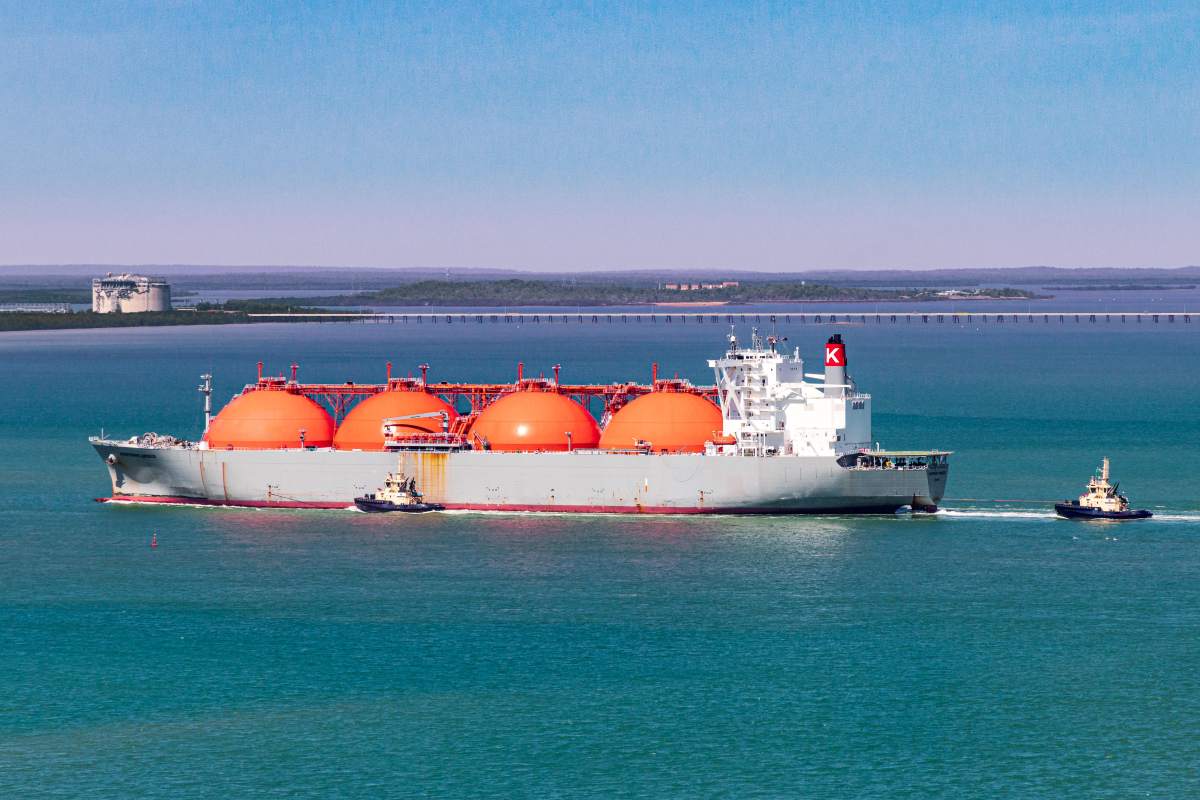
The liquefied natural gas market hit by crisis: -20% global supply. LNG prices at their highest since 2023
At a moment when energy markets were beginning to regain balance, the war in Iran and its repercussions have pushed liquefied natural gas back to the center of the global stage. The closure of the Strait of Hormuz has removed nearly 20% of global LNG supply, reigniting the price rally and driving volatility to elevated levels.
The IEA’s quarterly gas market report highlights how the system has been struck by a sudden shock, capable of reversing within weeks the stabilization trend recorded between late 2025 and early 2026.
Between October and February, global LNG supply had grown by 12% year-on-year, equal to +29 billion cubic meters, driven mainly by new capacity in North America. This increase had helped reduce prices, with Europe’s TTF falling by 24% and Asia’s JKM dropping by 27%.
The situation changed abruptly in March, when the blockade of the Strait disrupted flows from Qatar and the United Arab Emirates, which together represent a decisive share of global exports.
LNG vulnerable due to the closure of Hormuz
The core of the crisis lies in the Strait of Hormuz, through which around 20% of global LNG trade passes, equal to roughly 110 billion cubic meters per year.
The war in Iran and attacks on energy infrastructure led to an almost total suspension of exports from the Gulf. The result was an immediate drop in global LNG production, which in March fell by 8% year-on-year, with a loss of around 4 billion cubic meters.
In the short term, the consequences have been amplified by the structure of the market itself: liquefied natural gas flows depend on maritime logistics, and no alternative routes exist for the main Gulf exporters. In addition, around 90% of volumes transiting through Hormuz are destined for Asia, making these markets particularly exposed.
Natural gas returns to energy crisis levels
The most immediate impact has been on prices. In March, natural gas benchmarks reached their highest levels since the 2022–2023 crisis. In Europe, the TTF averaged $18 per MBtu, while in Asia the JKM approached $21 per MBtu.
Even more significant was the surge in volatility. The TTF volatility index rose to 160%, while the Asian benchmark reached nearly 300%, signaling an extremely unstable market.
The crisis also reversed trade flows. The price differential pushed LNG cargoes from Europe to Asia, where the premium reached $2.8 per MBtu.
Demand declines in favor of renewables
Faced with rising prices, global natural gas demand has started to decline, especially in major importing countries.
In Europe, consumption fell by around 4% in March, supported by higher renewable energy production, which reduced gas use in electricity generation.
In Asia, several governments responded by introducing demand containment measures. These include increased reliance on coal-fired power generation, the reactivation or expansion of nuclear capacity, and reduced consumption in energy-intensive sectors.
This combination of measures is accelerating fuel switching, replacing natural gas with other energy sources that are more available or less expensive in the short term. According to the report, this dynamic could reduce global gas demand by up to 60–65 billion cubic meters annually.
The role of liquefied natural gas in energy systems
Despite the crisis, liquefied natural gas confirms its central role in global energy security. In Europe, during the winter of 2025–2026, LNG imports reached a record 104 billion cubic meters, covering more than 40% of gas supply.
This figure highlights how LNG has become a structural energy source, particularly in a context of declining pipeline supplies and falling domestic production.
At the same time, extreme weather events, such as cold waves in the United States, Europe, and Asia, have demonstrated the importance of gas flexibility in ensuring power system reliability.
The Iran war will have lasting effects
Beyond the immediate impact, the crisis is also reshaping long-term prospects for the liquefied natural gas market.
Damage to facilities in Qatar and delays in expansion projects are slowing the so-called “LNG wave”, the new wave of production capacity expected in the second half of the decade.
According to the IEA, this will result in a cumulative loss of around 120 billion cubic meters of LNG between 2026 and 2030, equal to about 15% of the expected global supply over the same period.
The estimated delay is at least two years, with the most significant impacts expected between 2026 and 2027, prolonging a market phase characterized by tight supply and high prices.
Energy security and new global gas balances
The crisis highlights a structural vulnerability of the global energy system: dependence on a limited number of logistical chokepoints and major exporters.
For the IEA, addressing these vulnerabilities requires strengthening the overall architecture of energy security. This includes, first and foremost, greater diversification of supply sources to reduce exposure to single points of disruption such as the Strait of Hormuz.
At the same time, investments are needed across the entire liquefied natural gas value chain, from liquefaction infrastructure to maritime logistics and regasification terminals.
This must be accompanied by stronger international cooperation between producer and consumer countries, essential to managing emergency situations and ensuring stable energy flows.
In this context, long-term contracts are regaining importance as a tool to reduce exposure to spot market volatility.